Cash Visibility and Treasury Forecasting Technology UK SMEs | Nexteck
Learn how UK SMEs can improve cash visibility, multi-account monitoring, liquidity forecasting and financial planning through connected business account technology.
Cash Visibility Technology UK SMEs
Treasury Forecasting Software UK, Business Cash Flow Visibility, Multi-Account Cash Management, SME Treasury Management, Business Liquidity Planning, Cash Flow Forecasting Technology, Multi-Entity Finance Management, Business Banking Integration, Financial Reporting Automation, UK SME Financial Technology.
Target Audience: UK SMEs, growing companies, finance directors, business owners, multi-entity organisations, finance managers and businesses operating multiple bank accounts.
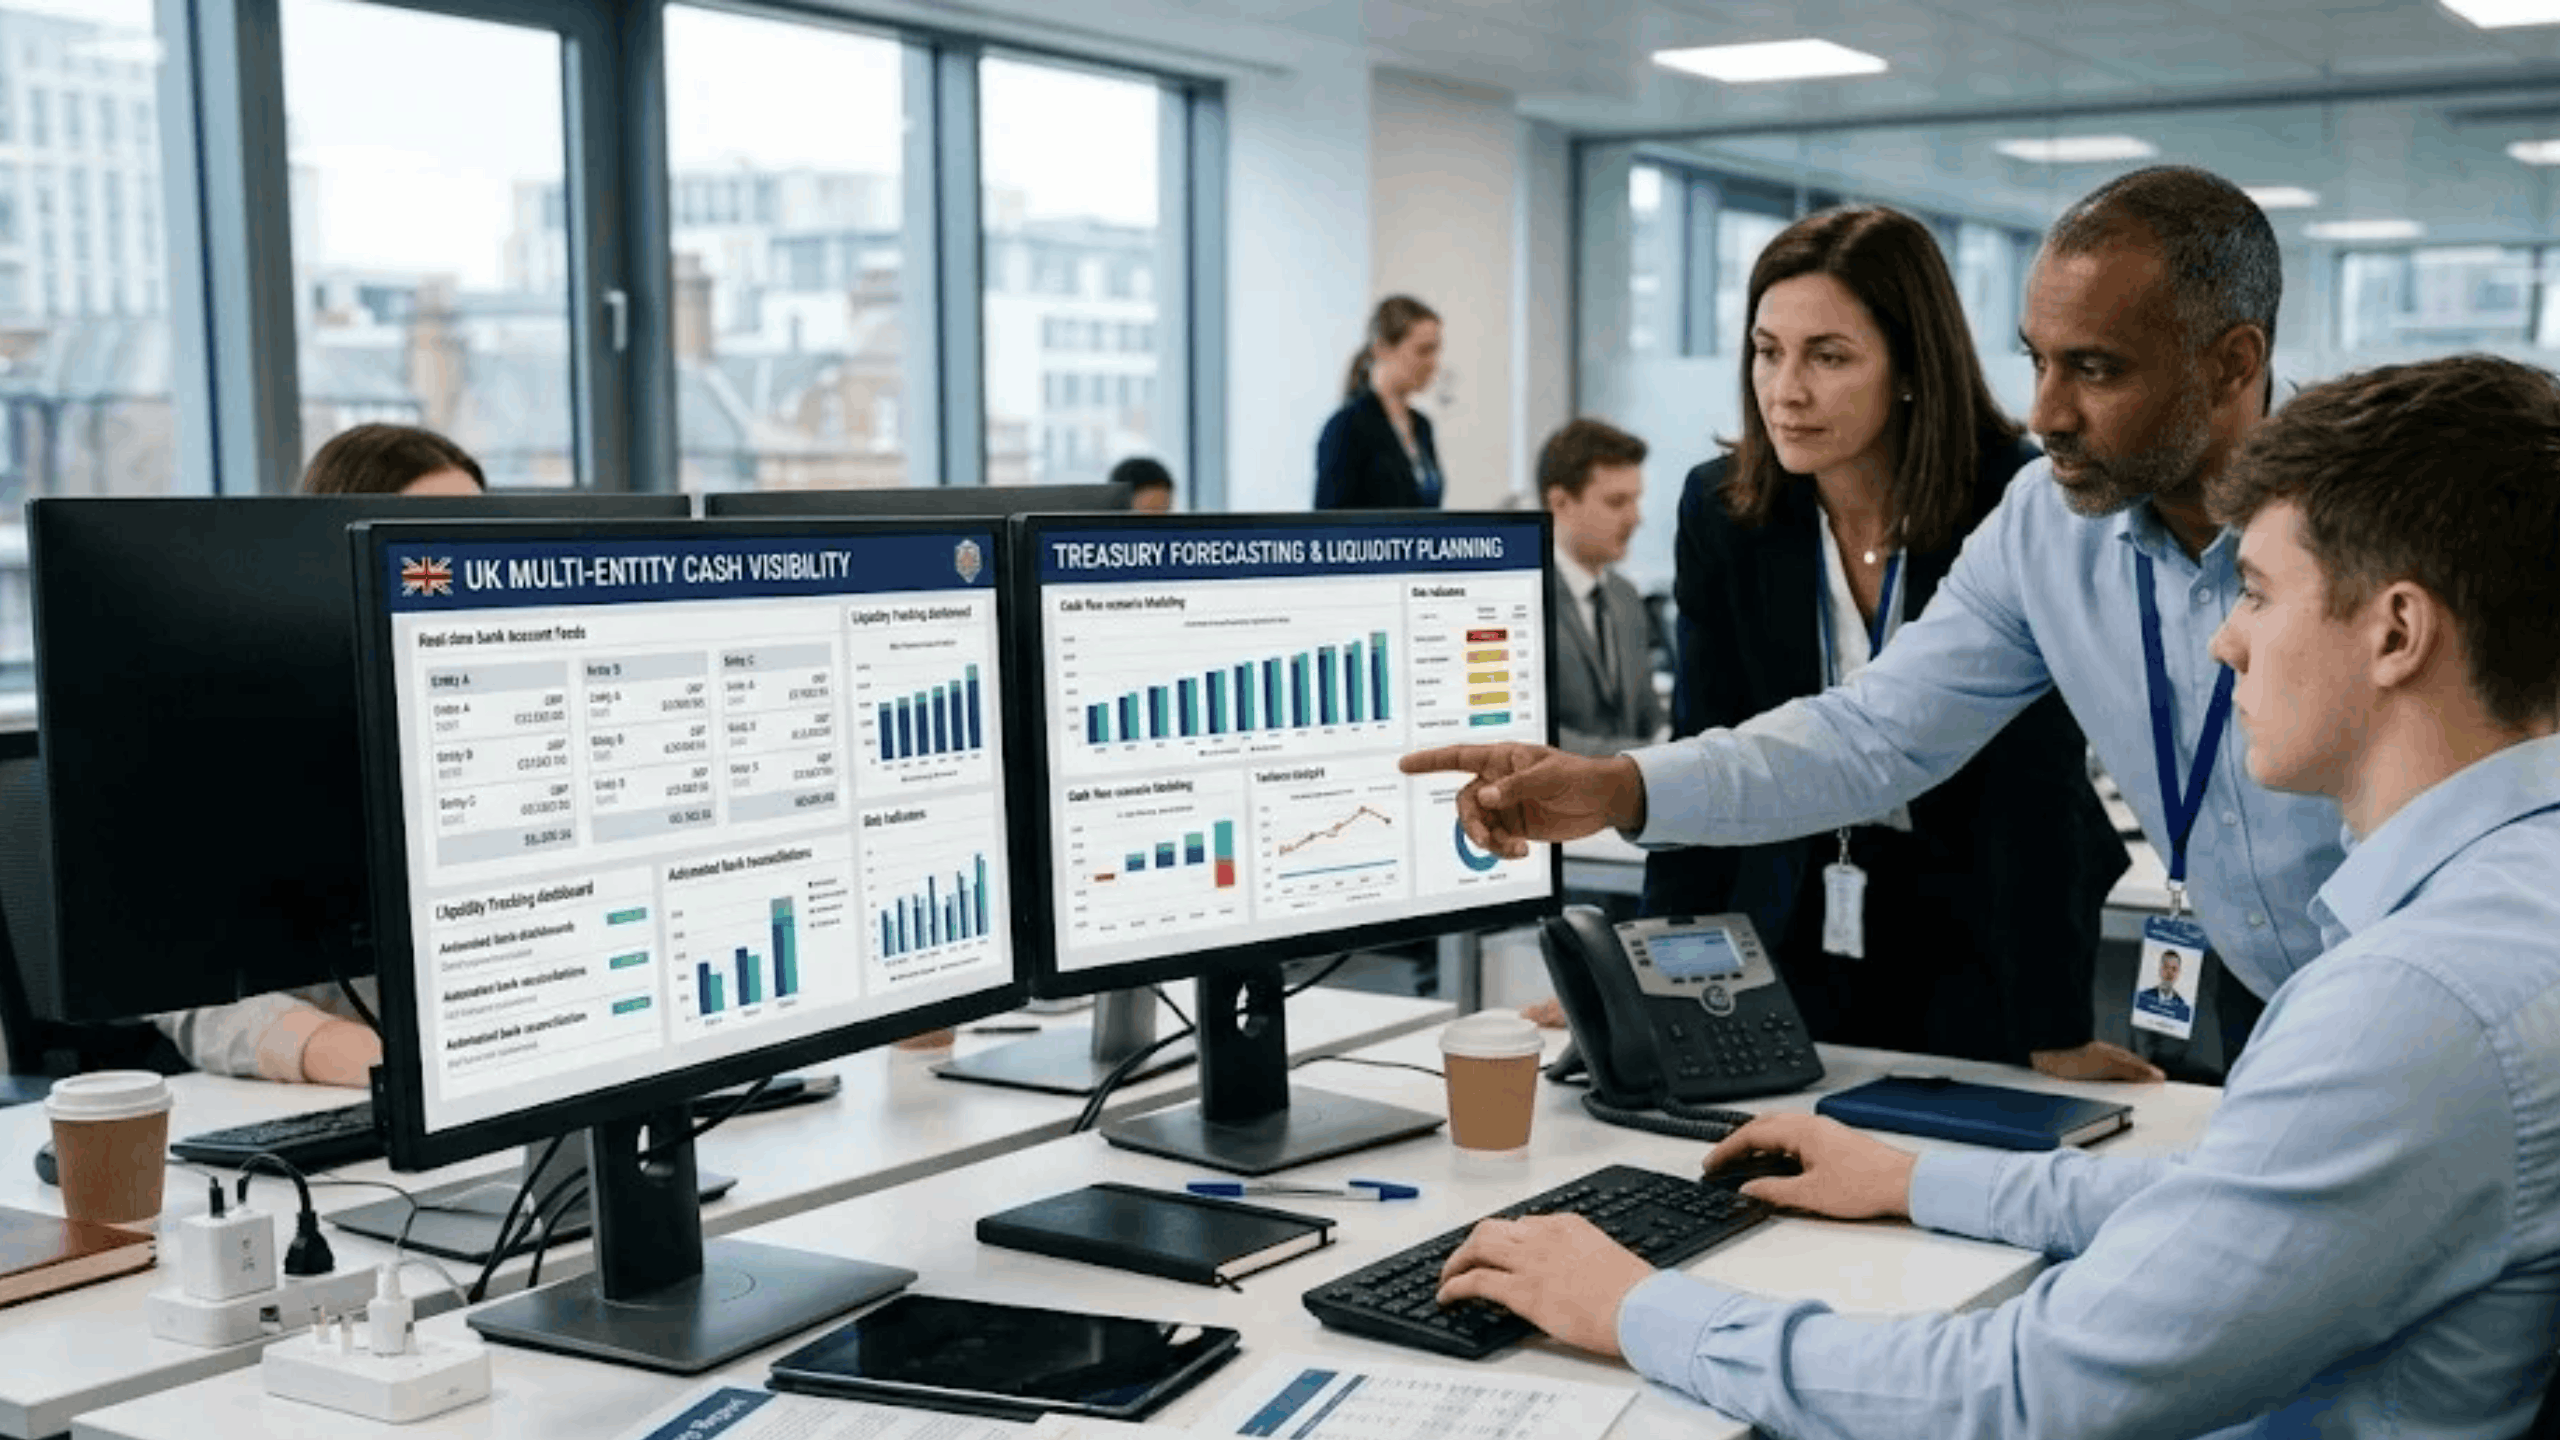
Multi-Entity Cash Visibility and Treasury Forecasting Technology for UK SMEs
Managing business finances becomes more complicated as a company grows.
A small business may initially operate with one current account, a basic accounting application and a spreadsheet for cash flow planning. As the organisation expands, it may open additional bank accounts, establish separate trading entities, operate different departments or introduce new payment channels.
The result can be fragmented financial information.
One account may hold customer receipts, another may be used for supplier payments, while separate accounts manage payroll, tax obligations, reserves or international transactions. For organisations operating multiple legal entities, financial information may be spread across several banking providers and accounting platforms.
Although every account may contain accurate information individually, management may struggle to understand the organisation's overall cash position.
This is where multi-entity cash visibility and treasury forecasting technology becomes valuable.
A connected financial environment can help businesses consolidate authorised account information, understand upcoming financial commitments, monitor liquidity and prepare more informed cash flow forecasts.
For UK SMEs, the goal is not simply to display multiple bank balances on one screen. It is to create a reliable financial view that supports planning, accountability and better operational decisions.
1. What Is Cash Visibility?
Cash visibility refers to the ability of a business to understand its available cash, expected inflows, upcoming outflows and overall liquidity position.
It requires more than checking the balance of a single bank account.
A business may have money distributed across several accounts, but some of that money may already be committed to supplier invoices, payroll, tax payments or other obligations.
For example, a company may have:
A main operating account.
A separate payroll account.
A VAT or tax reserve account.
A savings or reserve account.
An international transaction account.
Separate accounts for different legal entities.
Without consolidated reporting, management may need to log into several banking platforms and manually combine information.
A cash visibility solution helps bring relevant information together, subject to banking connectivity, permissions and data availability.
2. Why Growing UK SMEs Need Multi-Account Financial Visibility
As a business grows, financial responsibilities often become more distributed.
Different departments may manage their own expenditure, while finance teams oversee payments across multiple accounts.
This creates several operational challenges.
Fragmented balances: Managers may not have a single view of available funds across business accounts.
Delayed information: Bank transactions may not appear in internal reports immediately.
Manual consolidation: Finance employees may download statements and combine figures in spreadsheets.
Limited entity-level reporting: Businesses with multiple legal entities may struggle to compare their financial positions.
Unclear payment commitments: Available balances may not reflect invoices and other payments due shortly.
Inconsistent reporting: Different systems may use different categories, date formats or account identifiers.
These challenges can make financial planning reactive rather than proactive.
A structured technology approach can help improve visibility while keeping the underlying financial records accurate.
3. Creating a Consolidated Business Account View
A centralised cash dashboard can provide an overview of authorised business accounts.
Depending on the organisation's structure, it may display:
Account name and identifier.
Legal entity or business unit.
Bank or financial provider.
Current reported balance.
Available balance, where provided.
Currency.
Latest transaction update.
Pending transactions, where supported.
Account status and connection health.
The system should clearly distinguish between current balances, available balances and internally calculated estimates.
For example, an account balance retrieved from a bank feed is not necessarily the same as cash available after considering outstanding supplier payments.
A reliable dashboard should show when information was last updated and identify any disconnected or delayed data sources.
Businesses assessing their wider technology requirements can explore Nexteck's business technology and architecture services to understand how financial systems can be connected.
4. Managing Cash Across Multiple Legal Entities
Some UK businesses operate through several legal entities.
For example, a group may have a parent company and separate subsidiaries for different services, locations or commercial activities.
Each entity may have its own bank accounts, financial statements, payment obligations and accounting records.
Combining all balances into one figure without preserving entity-level information can create confusion.
A suitable financial reporting architecture should allow users to view:
Group-level cash position: A consolidated overview across relevant entities.
Entity-level cash position: Separate information for each legal entity.
Account-level information: Individual balances and transactions.
Currency-level reporting: Cash held in different currencies.
Intercompany movements: Transfers between related entities, recorded with appropriate references and accounting treatment.
Intercompany transfers should not be treated as external group revenue or expenditure simply because money moves between two accounts.
The reporting model should preserve the distinction between internal transfers and genuine third-party transactions.
For businesses reviewing multi-sector or multi-entity requirements, Nexteck's industry capabilities offer a useful starting point for considering different operating environments.
5. Connecting Banking Data with Accounting and Finance Systems
A major part of cash visibility is reliable data integration.
Businesses may use online banking platforms, accounting applications, payment providers, payroll systems and financial reporting tools.
If these systems operate independently, finance employees may need to repeat the same work across several applications.
A connected architecture can exchange authorised information between:
Business banking platforms.
Accounting software.
Enterprise resource planning systems.
Payment processing applications.
Payroll platforms.
Expense management systems.
Business intelligence dashboards.
Depending on provider capabilities, integrations may use open banking connections, approved APIs, bank statement files or secure data exchange processes.
The integration should define:
Which accounts can be accessed.
Which data fields are required.
How frequently information is refreshed.
How duplicate transactions are identified.
How missing or delayed records are handled.
Who can view or manage the information.
Not all banking providers expose the same functionality, and access to balances or transaction data depends on the relevant permissions and supported services.
6. Improving Cash Flow Forecasting
A consolidated view of bank balances is useful, but businesses also need to understand what may happen next.
Cash flow forecasting estimates future cash inflows and outflows over a selected period.
A forecast may consider:
Expected income: Customer invoices, recurring revenue, contract payments and other anticipated receipts.
Supplier commitments: Approved invoices, scheduled payments and recurring supplier expenses.
Payroll obligations: Salary payments, employer costs and related commitments.
Tax liabilities: VAT, PAYE, corporation tax and other applicable obligations.
Financing commitments: Loan repayments, interest and agreed finance payments.
Operational expenditure: Rent, utilities, subscriptions and other regular costs.
A technology-supported forecasting process can combine historical transactions with planned financial commitments.
However, forecasts should not treat every expected receipt as guaranteed income. They should distinguish confirmed, probable and uncertain cash movements.
For example, an invoice that has been issued but not paid should not be treated in the same way as cash already received.
7. Scenario Planning for Better Financial Decisions
Cash flow forecasts are based on assumptions. Those assumptions can change.
A customer may pay late, a major supplier invoice may arrive earlier than expected, or a business may experience an unexpected increase in operating costs.
Scenario planning helps finance teams understand how different conditions could affect liquidity.
A business could model:
Base case: Expected receipts and payments follow the current operating plan.
Delayed-receipts case: Selected customers pay later than anticipated.
Increased-cost case: Operating expenses or supplier costs rise.
Growth case: Higher sales volumes require additional inventory, staffing or operating expenditure.
Investment case: The business makes a planned capital expenditure or expansion investment.
The objective is not to predict the future perfectly. It is to understand how different assumptions affect the organisation's cash position.
Forecast assumptions should be documented and reviewed regularly.
8. Building Useful Treasury and Cash Management Dashboards
A cash dashboard should help business leaders answer practical questions quickly.
Examples include:
How much cash is held across the organisation?
Which entities have the highest and lowest liquidity?
Which payments are due over the next 7, 30 or 90 days?
Which customer receipts remain outstanding?
Which accounts have not updated recently?
How does the forecast compare with actual cash movements?
What happens if important customer payments are delayed?
Useful KPIs may include:
| KPI | Purpose |
|---|---|
| Consolidated cash balance | Total reported cash across selected accounts |
| Available liquidity | Cash available under the defined reporting method |
| Forecast closing balance | Expected balance at the end of a period |
| Cash runway | Estimated period current resources can support operations under stated assumptions |
| Receivables ageing | Outstanding customer invoices by age |
| Payables due | Supplier payments expected within a period |
| Forecast variance | Difference between forecast and actual cash movement |
| Account data freshness | How recently account information was updated |
| Minimum liquidity threshold | Internal cash level requiring management attention |
A dashboard should make the assumptions behind its calculations clear.
For example, a cash runway estimate depends on the expenditure assumptions and time period used. It should not be presented as a guaranteed measure of business survival.
9. How AI Can Support Cash Flow Forecasting
Artificial intelligence can help finance teams organise financial information and identify patterns.
Potential applications include:
Categorising historical transactions.
Identifying unusual spending patterns.
Preparing summaries of cash flow movements.
Highlighting changes in receivables and payables.
Supporting scenario analysis.
Drafting explanations for forecast variances.
Searching approved financial policies and reporting documents.
For example, an AI-assisted reporting system may identify that a particular expense category has increased compared with previous periods and prepare a summary for finance team review.
However, AI-generated forecasts should be treated as decision-support information.
Finance teams should validate the underlying data, review assumptions and retain control over significant financial decisions.
AI should not independently initiate bank transfers or approve payments merely because a forecast suggests that funds are available.
10. Financial Security, Permissions and Governance
A centralised cash management platform may bring sensitive financial information into one environment.
That makes security and governance essential.
Businesses should consider:
Role-based access: Employees should only see the accounts and information required for their responsibilities.
Multi-factor authentication: Appropriate authentication controls should protect financial systems.
Read-only integrations: Where possible, cash visibility connections should use read-only access when payment initiation is not required.
Approval separation: Viewing balances, preparing payment instructions and approving payments should be separate permissions where appropriate.
Audit trails: Changes to account connections, reporting settings and financial records should be logged.
Secure data handling: Financial data should be protected during transmission and storage.
Access reviews: Permissions should be reviewed when employees change roles or leave the organisation.
UK businesses should also consider relevant financial services requirements, contractual obligations and data protection responsibilities, including UK GDPR where personal data is processed.
11. A Practical Implementation Roadmap for UK SMEs
Introducing multi-account cash visibility does not need to begin with a complete replacement of existing financial software.
A phased approach is often more practical.
Phase 1 – Financial process review
Identify all relevant bank accounts, legal entities, accounting platforms and reporting responsibilities.
Phase 2 – Data and access assessment
Review available banking connections, account permissions, data formats and information security requirements.
Phase 3 – Standardise financial records
Define consistent entity identifiers, account categories, transaction references and reporting periods.
Phase 4 – Establish consolidated reporting
Build an initial view of authorised accounts while preserving account-level and entity-level detail.
Phase 5 – Introduce forecasting
Combine account information with approved receivables, payables, payroll and other planned commitments.
Phase 6 – Add scenario planning
Create base, delayed-income and increased-cost scenarios to support financial planning.
Phase 7 – Monitor and improve
Compare forecasts with actual results, review data quality and update assumptions.
The Nexteck SME Strategy & Tracking Toolkit can help businesses organise their technology priorities, document operational gaps and track implementation actions.
12. Choosing the Right Cash Visibility Technology
The right solution depends on the organisation's banking providers, account structure, transaction volume and reporting requirements.
Before selecting a platform, UK SMEs should evaluate:
Can the solution connect to the required business bank accounts?
Does it support multiple legal entities?
Can it display different currencies?
How frequently is account information updated?
Can it connect with existing accounting applications?
Does it distinguish actual balances from forecast figures?
Can it support cash flow scenarios?
Are access permissions and audit trails available?
Can reports be exported for management and finance reviews?
What happens when a banking connection fails?
A standard cash management platform may be sufficient for a business with a straightforward account structure.
A growing organisation with multiple entities, currencies and complex financial processes may require additional integration or custom reporting capabilities.
The best solution is one that provides accurate, understandable information without introducing unnecessary operational complexity.
Frequently Asked Questions
What is multi-account cash visibility?
Multi-account cash visibility is the ability to view and analyse financial information across multiple authorised business bank accounts from a consolidated reporting environment.
Why is cash visibility important for UK SMEs?
It helps businesses understand their reported cash position, upcoming obligations and potential liquidity requirements, supporting more informed financial planning.
Can businesses connect multiple bank accounts to one dashboard?
Yes, where supported banking connections and permissions are available. The dashboard can consolidate relevant account information while retaining individual account details.
What is the difference between cash visibility and cash flow forecasting?
Cash visibility focuses on understanding current reported cash positions. Cash flow forecasting estimates future inflows, outflows and balances using financial data and documented assumptions.
Can cash visibility systems support multiple companies?
Suitable systems can support multiple legal entities and accounts, provided the underlying data model preserves entity-level information and appropriate accounting treatment.
Can AI improve cash flow forecasting?
AI can help analyse historical transactions, identify patterns and support scenario modelling. Forecast assumptions and important financial decisions should remain subject to finance team review.
Is open banking required for multi-account cash management?
Not necessarily. Depending on provider capabilities and business requirements, information may be accessed through open banking, approved APIs, secure bank statement files or other supported methods.
How often should a business review its cash flow forecast?
The frequency depends on cash flow volatility and operational requirements. Some businesses review forecasts weekly, while others may require more frequent monitoring.
Build Better Financial Visibility Across Your Business
A growing business needs more than a collection of separate bank balances. It needs a reliable understanding of cash availability, upcoming financial commitments and the financial position of each part of the organisation.
Multi-account cash visibility and treasury forecasting technology can help UK SMEs reduce manual reporting, improve financial planning and identify potential liquidity pressures earlier.
Nexteck helps businesses assess their technology architecture, identify disconnected systems and plan practical integration improvements.
Explore Nexteck's technology and advisory services, review its industry capabilities and use the SME Strategy & Tracking Toolkit to organise your next technology improvement priorities.
Connected financial information. Clearer cash visibility. Better-informed business decisions.